
The Middle East and Global Energy Markets
Key facts on the Strait of Hormuz, oil and gas markets, and the IEA’s response
The IEA is responding to the energy market impacts of the conflict in the Middle East and continues to closely monitor developments. The latest statement on energy markets and security from the IEA's Governing Board, published on 15 October, can be found here.
The disruption to oil and gas flows through the Strait of Hormuz and attacks on energy infrastructure across the region have major implications for energy security and affordability – and for the world economy.
The IEA's Executive Director has said the combined impacts amount to "the greatest threat to global energy security in history." The war in the region that began on 28 February has impeded energy trade flows through the Strait, creating the largest supply disruption in the history of the global oil market. Global gas markets have also been affected; about 20% of the world's supply of liquefied natural gas (LNG) moved through the Strait in 2025.
On 11 March, IEA Member countries unanimously agreed to carry out the Agency’s largest-ever release of emergency oil stocks to help address the market disruptions. Read the latest update on the stock release here.
Current market backdrop
Oil and natural gas prices have experienced significant volatility since the war began. In the wake of the largest oil supply disruption in history, Brent futures – the global benchmark for crude prices – rose steeply, peaking at more than 60% above pre-conflict levels in late April. Prices then eased as strategic stock releases, a ceasefire agreement and lower demand helped reduce concerns about market tightness, but they rose again in September and October amid the return of hostilities. They have since pulled back as the market shows tentative signs of rebalancing, although they remain above pre-war levels.
Through ship-to-ship transfers and alternative export routes to the Strait of Hormuz, crude oil exports from Gulf producers have been rising since August. In October, they reached 15 million barrels per day, more than 80% of pre-war levels, according to our latest Oil Market Report. This has helped lift global oil supply above demand for the first time since the war began – although continued attacks on ships in the region pose ongoing risks and threaten a more sustained recovery.
Markets for refined oil products remain particularly tight. In 2025, Gulf producers exported 3.3 million barrels per day of refined oil products and 1.5 million barrels per day of liquefied petroleum gas. Volumes are now at roughly half of prewar levels. Meanwhile, persistent attacks on Russian energy infrastructure continue to choke off oil product supplies to international markets.
As a result of these pressures, diesel markets are under significant strain. Losses of the petrochemical feedstocks used to produce plastics, chemical products and fertilisers are also still mounting.
The tentative market rebalancing has begun to ease pressure on global oil inventories, which rose in October for the first time since June – although observed stocks have fallen by a cumulative 462 million barrels since the start of the war.
In this episode, IEA experts discuss how escalating attacks on ships transiting the Strait of Hormuz and on energy infrastructure across the Middle East threaten to derail the recent recovery in the region’s oil exports.
The war has also disrupted both regional and global market dynamics for natural gas, reversing a trend of market rebalancing that had been underway during the 2025/26 heating season. The disruption of transit via the Strait of Hormuz has reduced LNG supplies from Qatar and the United Arab Emirates by over 300 million cubic metres per day since 1 March – which translates into a loss of over 2 billion cubic metres of gas supply every week. However, around three-quarters of the losses since the beginning of March have been offset by a very strong increase in LNG supply from other producing regions.
The Ras Laffan facility in Qatar, which is the world's largest liquefaction facility, has been offline since an attack on 2 March. Regional gas production is also affected by the shutting in of oil fields, which has reduced the output of gas associated with oil production.
Spot natural gas prices in Asia and Europe reacted swiftly to the supply shock. In March, they reached their highest monthly averages since January 2023, and they remain well above their 2025 levels. This has contributed to a contraction in natural gas demand in key LNG importing markets.
The conflict has also altered the medium-term outlook for global natural gas markets. According to our latest quarterly Gas Market Report, damage to LNG liquefaction infrastructure in Qatar is set to reduce projected supply growth, delaying the anticipated global LNG supply wave. Short-term supply losses and slower capacity growth could result in a cumulative loss of around 140 billion cubic metres of LNG supply between 2026 and 2030. While new liquefaction projects in other regions are expected to offset these losses over time, the impacts of these disruptions could be felt through 2026 and 2027.
Our 2026 Energy Crisis Policy Response Tracker catalogues government actions to curb demand and support consumers in response to the energy market impacts of the conflict, while our new interactive tool shows the reliance of different countries on oil and gas supplies from the Middle East.
IEA’s role and oil stock release
Ensuring energy security has been at the centre of the IEA’s mission since its founding in 1974 following the major oil crisis the year before. A critical aspect of this work has been to help coordinate collective responses to major oil supply disruptions by providing additional oil to the global market on a short-term basis.
Each of the IEA’s 32 Member countries has an obligation to hold oil stocks equivalent to at least 90 days of net oil imports and to be ready to collectively respond to severe supply disruptions affecting the global oil market.
On 11 March, IEA Member countries unanimously agreed to take emergency collective action to respond to the major disruptions in oil markets, making 400 million barrels of emergency oil stocks available – the largest-ever release coordinated by the Agency.
The stock release largely consists of crude oil, while in Europe, the contributions are primarily taking the form of refined oil products. This is being complemented by additional production from countries in the Americas. The latest details are available here.
The coordinated stock release is the sixth in the history of the IEA. Previous collective actions were taken in 1991, 2005, 2011, and twice in 2022.
The IEA continues to assess the energy security implications of the situation in coordination with governments around the world. A new report, Sheltering from Oil Shocks, also outlines demand-side measures that governments, companies and households can take to help ease price pressures on consumers.
And the IEA, International Monetary Fund, World Bank and World Trade Organization have formed a coordination group to maximise their responses to the energy and economic impacts of the war. Their latest statement is available here.
Why is the Strait of Hormuz so important?
The Strait of Hormuz is a narrow sea passage, separating the Arabian Peninsula and Iran, and connecting the Persian Gulf with the Gulf of Oman and the Arabian Sea. A crucial trade artery, it is the primary export route for oil and natural gas produced by Saudi Arabia, the UAE, Kuwait, Qatar, Iraq, Bahrain and Iran.
Traffic through the Strait has been essentially halted by the conflict, putting pressure on the trade of a wide range of energy products.
Around 25% of the world’s seaborne oil trade transited the Strait in 2025, and options for oil flows to bypass the Strait of Hormuz are limited. Only Saudi Arabia and the UAE have operational crude pipelines that could potentially reroute flows to bypass the Strait, with an estimated 3.5 million barrels per day to 5.5 million barrels per day of available capacity. Other countries, including Iran, Iraq, Kuwait, Qatar and Bahrain, rely on the Strait to deliver the vast majority of their oil exports.
Alternative routes
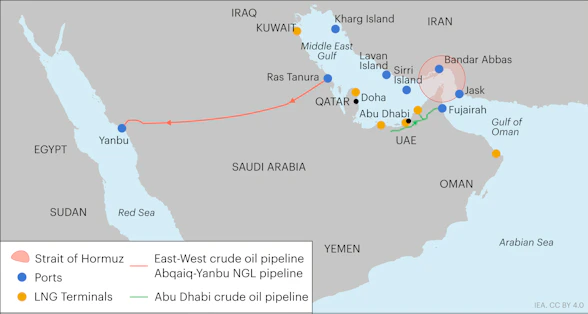
About 80% of oil and oil products transiting the Strait in 2025 was destined for Asia.
In addition, over 110 bcm of LNG passed through the Strait of Hormuz in 2025. About 93% of Qatar’s and 96% of the UAE’s LNG exports transited through the Strait, representing almost one-fifth of global LNG trade. There are no alternative routes to bring these volumes to market.
Most LNG from Qatar and the UAE goes to Asia. In 2025, almost 90% of the total volumes exported via the Strait of Hormuz was destined for the Asian market – accounting for more than a quarter of the region's total LNG imports. Just over 10% went to Europe.
Crude oil exports transiting the strait of Hormuz by destination, 2025

Total does not match sum of adding individual numbers due to destinations not indicated. Source: IEA analysis based on Kpler.
Oil products transiting the strait of Hormuz by destination, 2025
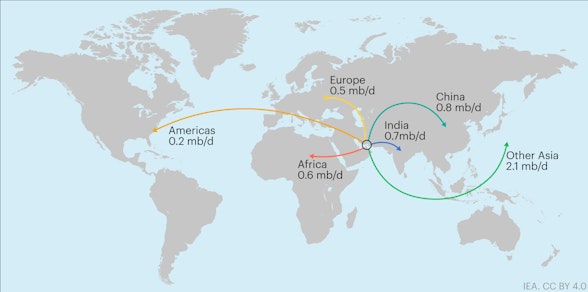
Total does not match sum of adding individual numbers due to destinations not indicated. Source: IEA analysis based on Kpler.
More information about the Strait of Hormuz
Impact on other key commodities
Various other commodities markets have also been affected by disruptions to shipping in the Strait of Hormuz, with implications for energy and beyond.
Fertiliser supply is particularly exposed. More than 30% of global trade of urea moves through the Strait, along with about 20% of trade of ammonia and phosphate. This creates risks for food prices and security. Moreover, disruptions in this sector could have indirect effects on energy markets, since some countries use imported LNG to run domestic fertiliser plants.
Additionally, the Gulf region produces around 8% of the global supply of aluminium, which is used in numerous energy technologies, as well as in construction and manufacturing. About 5 million tonnes of the metal are shipped each year through the Strait from smelters in Bahrain, Qatar, Saudi Arabia and the United Arab Emirates.
Around half of global seaborne sulphur trade also moves through the Strait of Hormuz. Sulphuric acid is used not only to produce fertiliser and chemicals, but also in the refining of petroleum and critical minerals such as copper, nickel and zinc.